What is the scope and industry significance of the Document Scanning Services Market?
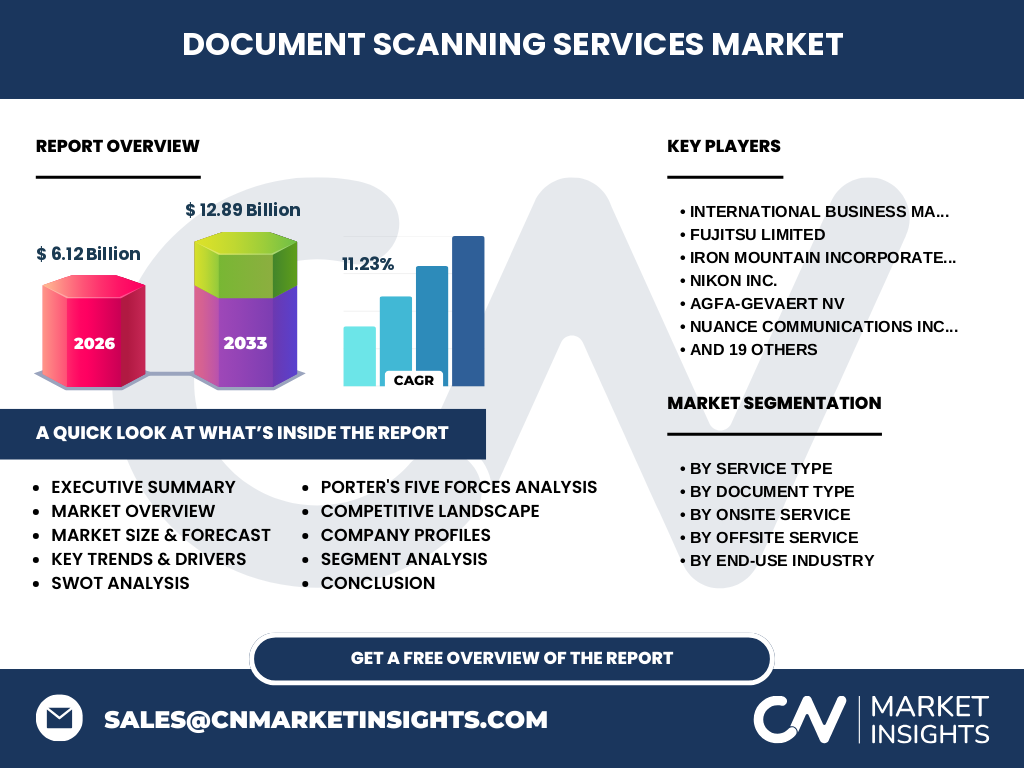
Our analysis indicates that the Document Scanning Services Market represents a critical pillar of digital transformation, valued at 6.12 Billion in 2026. This sector encompasses advanced conversion technologies that migrate physical archives into structured digital assets, supporting rigorous regulatory frameworks such as HIPAA and GDPR across global enterprises.
Key market drivers, restraints, challenges, and opportunities shaping the Document Scanning Services Market
The market is propelled by strict compliance mandates and remote work demands, though high initial capital expenditures for specialized optical character recognition hardware remain a restraint. Opportunities abound in automated data capture workflows, enabling providers like Ripcord Inc. and KnowledgeLake to capture massive enterprise upgrade cycles.
Emerging trends and growth patterns in the Document Scanning Services Market
The integration of artificial intelligence and machine learning into Cloud-based Scanning Services is redefining efficiency. Our research shows that automated metadata extraction and intelligent document processing are replacing manual indexing, sharply reducing error rates in high-volume legal and medical environments.
COVID-19 impact analysis and recovery trajectory
The pandemic forced a rapid pivot toward decentralized operations, causing a temporary dip in onsite scanning contracts while accelerating demand for Mobile Or Remote Document Scanning. Recovery has been swift and robust, driven by permanent enterprise commitments to hybrid workforce models and cloud-native document repositories.
Competitive landscape and strategic dynamics
Market concentration features a mix of diversified technology giants like Fujitsu Limited and Eastman Kodak Company alongside specialized records managers like Iron Mountain Incorporated. Strategic positioning increasingly relies on proprietary software ecosystems that bundle hardware capture with intelligent cloud archiving.
Executive summary of key findings
Driven by an exceptional CAGR of 11.23%, the market is projected to surge from 6.12 Billion in 2026 to 12.89 Billion by 2033. Enterprises across BFSI and healthcare are heavily prioritizing automated digitization over legacy physical storage to mitigate operational risks.
Market forecast from 2027 to 2033
Backed by consistent double-digit expansion, the industry will scale from its 2026 baseline to reach 12.89 Billion by 2033. This trajectory reflects accelerated adoption of automated workflows and stringent data retention laws in developing economies.
Segmentation analysis across services and document types
Segmentation spans Onsite Service and Offsite Service, alongside specialized document categories including Medical Record Scanning, Legal Document Scanning, and Blueprint And Map Scanning. Each segment addresses distinct regulatory compliance and retrieval speed requirements across target industries.
Regional market analysis and geographic distribution
Geographic performance is heavily concentrated in North America and Europe due to mature legal frameworks and high enterprise density. Asia-Pacific is rapidly emerging as the fastest-growing region, fueled by aggressive government-backed digitalization initiatives and expanding corporate IT infrastructure.
In-depth regional review of key markets
North America commands the largest market share, sustained by stringent compliance requirements in healthcare and finance. Meanwhile, the EMEA market exhibits strong steady growth, heavily influenced by strict European data privacy regulations that necessitate secure, localized document archiving solutions.
Company profiles and strategic positioning
Industry leaders leverage distinct competitive moats: Iron Mountain Incorporated dominates physical and digital storage integration, whereas Nuance Communications Inc. and KnowledgeLake focus on advanced text recognition software. Firms like Flatworld Solutions Private Limited capitalize on cost-effective offshore data processing capabilities.
Porter's Five Forces analysis of competitive intensity
Competitive rivalry is intense among established scanning bureaus, while supplier power remains moderate due to standardized scanning hardware. The threat of substitution is low given the complex legal admissibility standards attached to certified digital document conversions.
SWOT analysis of the sector
Strengths include high switching costs and sticky enterprise contracts. Weaknesses involve vulnerability to supply chain disruptions for scanner components. Opportunities lie in AI-driven data analytics, while major threats stem from sophisticated cybersecurity breaches targeting cloud repositories.
Value chain analysis from raw materials to end-users
The value chain originates with optical sensor manufacturers and software developers, flowing through specialized service bureaus like Chicago Records Management Inc. and Pacific Records Management, ultimately delivering indexed, searchable archives to end-users in government and enterprise sectors.
Investment insights and high-potential areas
High-potential investment targets include niche providers specializing in Cloud-based Scanning Services and automated human resources record migration. Investors should prioritize firms demonstrating proprietary AI indexing capabilities that reduce manual labor overhead.
Conclusion and key takeaways
The Document Scanning Services Market represents a high-growth sector set to achieve 12.89 Billion by 2033. Organizations that successfully integrate AI-driven automation into their scanning portfolios will capture disproportionate market share.
Research methodology for baseline estimates
Our findings are triangulated through a rigorous methodology combining trade registry filings, primary executive interviews with bureau operators, and secondary macroeconomic indicators. This multi-tiered approach ensures high fidelity in market sizing and growth projections.
Scope of the report and coverage parameters
This report covers global deployment trends across eight core end-use industries and multiple service typologies from 2026 through 2033. Exclusions include purely internal corporate desktop scanning operations not serviced by commercial third-party vendors.
Recent developments in the industry
Recent strategic moves feature aggressive venture funding rounds for AI-first capture platforms like Ripcord Inc. and strategic service partnerships between legacy record archives and cloud providers. These initiatives highlight an industry-wide push toward touchless, automated document processing ecosystems.